Can I Get a Personal Loan With Bad Credit?
Yes, you can qualify for a personal loan even if your credit score is in the fair or poor range. While traditional retail banks and credit unions typically enforce strict FICO score minimums of 660 or higher, the lending ecosystem has expanded significantly. Modern online lenders look beyond a three-digit credit score, evaluating your current income stability, employment tenure, and debt-to-income (DTI) ratio.
In the standard FICO credit scoring model, credit scores are categorized as follows:
- Exceptional (800–850): Best interest rates and maximum borrowing limits.
- Very Good (740–799): Highly competitive rates from prime lenders.
- Good (670–739): Near-prime rates with wide approval availability.
- Fair (580–669): Subprime category where specialized personal loans become relevant.
- Poor / Bad (300–579): Deep subprime where lenders focus heavily on monthly cash flow and repayment ability.
Even if past financial hardships, medical emergencies, or unexpected layoffs caused derogatory marks on your credit profile, lenders in our network look for evidence that your financial situation is stable today.
Online Loan Options for Bad Credit
When searching for personal loans with poor credit, understanding the different loan products available will help you choose the safest and most affordable solution:
- Unsecured Personal Installment Loans: Borrowers receive a lump sum of $500 to $10,000 and repay it in equal monthly installments over 6 to 36 months. No collateral is required, meaning your personal property is not at risk of repossession.
- Secured Personal Loans: These loans require you to back the borrowing amount with collateral, such as a paid-off vehicle title or a savings certificate of deposit (CD). Because collateral reduces lender risk, secured loans may offer lower APRs or higher borrowing amounts.
- Co-Signed or Joint Loans: If your credit profile makes solo qualification difficult, applying with a creditworthy co-signer (such as a spouse or family member with good credit) can significantly improve approval odds and lower your borrowing rate.
- Credit Union Payday Alternative Loans (PALs): Federal credit unions offer small-dollar installment loans (PALs) with interest rates capped by federal law at 28.00% APR. Borrowers must be credit union members to qualify.
Comparing Loan Options for Bad Credit
| Loan Type | Typical Amount | Typical APR Range | Collateral Required | Credit Impact |
|---|---|---|---|---|
| Unsecured Installment Loan | $500 – $10,000 | 18.00% – 35.99% | None | Builds credit with on-time payments |
| Secured Personal Loan | $1,000 – $15,000 | 12.00% – 28.00% | Vehicle or Savings Account | Builds credit; risk of asset forfeiture |
| Co-Signed Personal Loan | $1,000 – $25,000 | 9.99% – 25.00% | None | Builds credit for both applicants |
| Credit Union PAL | $200 – $2,000 | Up to 28.00% (Federal Cap) | None | Positive reporting to credit bureaus |
| Payday Loan (To Avoid) | $100 – $1,000 | 300% – 600%+ | Post-dated check / ACH debit | Rarely reports on-time payments; debt trap risk |
How Bad Credit Loan Applications Work
Submitting a loan request through All Financial Help is designed to be streamlined, transparent, and secure:
- Submit Your Inquiry Online: Complete our 2-minute inquiry form specifying your desired loan amount ($500 to $10,000) and primary income source. The initial evaluation relies on a soft inquiry, allowing you to check options without affecting your credit score.
- Fast Partner Review: Our network of reputable online lenders reviews your information against their specific underwriting criteria, focusing on your monthly cash flow and affordability.
- Review Your Loan Offer & Disclosures: If connected with a lending partner, you will review a detailed loan offer outlining the exact APR, monthly payment amount, loan term, and repayment schedule in full accordance with the Truth in Lending Act (TILA).
- E-Sign and Receive Funds: After you carefully review and electronically sign the agreement, funds are disbursed directly to your checking account, often as soon as the next business day.
What Lenders Consider Besides Your Credit Score
When your FICO score is less than perfect, specialized online lenders evaluate alternative financial indicators to assess your ability to repay:
- Consistent Monthly Income: Lenders typically look for recurring verifiable income of at least $1,200 to $1,800 per month from employment, self-employment, Social Security, or retirement benefits.
- Debt-to-Income (DTI) Ratio: Your DTI represents the percentage of your gross monthly earnings dedicated to existing recurring debts. Lenders generally prefer a DTI below 45% to ensure you have sufficient margin to make monthly payments.
- Bank Account History: An active personal checking account in good standing with direct deposit history demonstrates financial stability. Lenders check for healthy cash flow and the absence of chronic overdraft or non-sufficient fund (NSF) fees.
- Employment & Residential Stability: Staying at the same employer and address for six months or longer signals lower risk to underwriters.
- Recent Payment Trends: A borrower who has made 12 consecutive months of on-time rent and utility payments is viewed much more favorably than someone with active, unresolved delinquencies.
Bad Credit Loan Amounts and APRs
Because lenders take on greater risk when funding borrowers with lower credit scores, interest rates on bad credit loans are higher than those on prime loans. However, legitimate online personal loans are strictly capped under state and federal regulations:
- Borrowing Amounts: Typically range from $500 to $5,000 for applicants with bad credit, with amounts up to $10,000 available for borrowers with strong verifiable income.
- APR Range: Annual Percentage Rates generally span from 18.00% to 35.99%. Leading consumer protection agencies, including the National Consumer Law Center (NCLC), regard 36% APR as the benchmark for responsible installment lending.
- Repayment Terms: Common loan durations range from 6 to 36 months, allowing you to choose a term that keeps your monthly installment within your monthly budget.
Representative TILA Repayment Example
For a personal loan of $2,500 borrowed over a 24-month term at an Annual Percentage Rate (APR) of 24.50%, your fixed monthly payment would be $133.09. The total amount repaid would be $3,194.16, representing a total finance charge of $694.16. All terms, fees, and payment obligations are disclosed in writing prior to loan acceptance.
How to Compare Available Loan Offers
Before accepting any loan offer, review these critical factors to ensure you are receiving the best available terms:
- Compare APR, Not Just Interest Rate: The APR includes both the base interest rate and any upfront origination fees, giving you the true annual cost of borrowing.
- Review Origination Fees: Some lenders charge an origination fee (typically 1% to 8%) deducted from the loan proceeds before disbursement. Make sure the net amount received covers your expense.
- Verify Monthly Payment Affordability: Confirm that the monthly installment fits comfortably within your budget without forcing you to sacrifice rent, groceries, or utilities.
- Check Prepayment Terms: Ensure the lender does not penalize you for paying off the loan early. All lenders in our network allow early payoff without penalty.
- Confirm Credit Reporting: Verify that the lender reports on-time payments to Experian, Equifax, or TransUnion so you receive credit-building benefits.
How to Improve Your Chances of Approval
Taking a few proactive steps before submitting your inquiry can meaningfully boost your likelihood of receiving competitive loan options:
- Request a Realistic Loan Amount: Asking for $1,500 to cover an urgent car repair is far more likely to receive partner offers than requesting $15,000 with a sub-600 credit score.
- Verify Income Information Carefully: Ensure your stated monthly earnings match what is shown on your pay stubs and bank deposits. Mismatches can delay or void an offer.
- Check Your Credit Reports for Errors: Visit AnnualCreditReport.com to inspect your reports. Inaccurate collections or paid debts showing as unpaid can drag down your score unnecessarily.
- Avoid Recent Bank Overdrafts: Keep a positive checking balance for at least 30–60 days before applying to demonstrate responsible cash management.
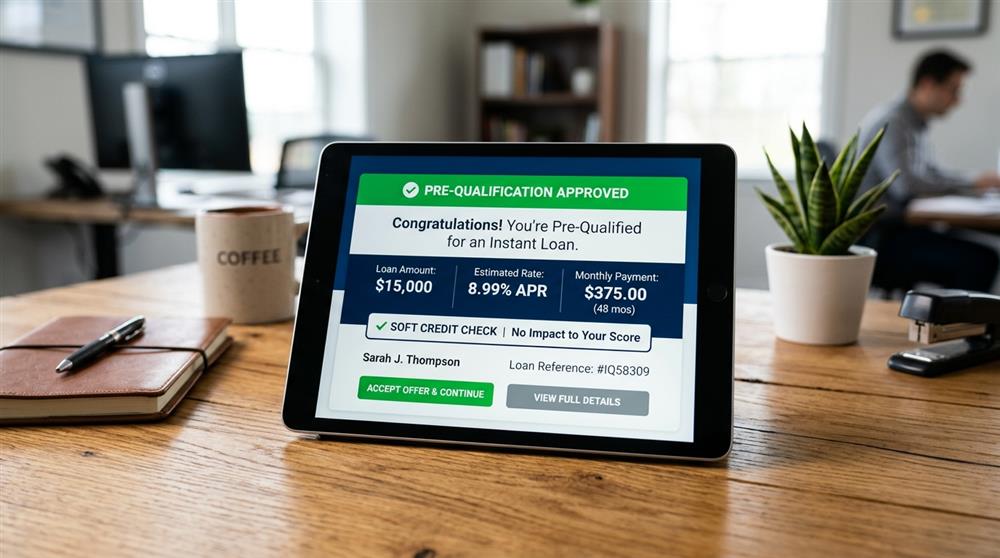
- Use Prequalification First: Always explore options through pre-qualification with soft credit inquiries before agreeing to a hard inquiry.
Basic Eligibility Criteria
- ✓ Must be at least 18 years of age (19 in Alabama and Nebraska)
- ✓ U.S. citizen or legal permanent resident
- ✓ Steady, verifiable monthly income of at least $1,200
- ✓ Active personal checking account in your name
Frequently Asked Questions About Bad Credit Loans
In the standard FICO scoring model, credit scores below 580 are classified as poor or bad credit, while scores between 580 and 669 are considered fair credit. Traditional banks typically decline applicants below 660, but specialized online lending partners evaluate monthly income, debt-to-income ratio, and banking history rather than relying on credit score cutoffs alone.
Yes. Most bad credit personal loans in our network are unsecured installment loans, meaning you do not have to pledge a vehicle title, savings deposit, or home equity as collateral. Approval is based on your current verifiable earnings and overall ability to afford the monthly installment.
No legitimate lender offers guaranteed approval. By federal lending guidelines, regulated lenders must evaluate a borrower's ability to repay before extending credit. Lenders advertising "100% guaranteed approval" are often predatory or fraudulent. Reputable lenders offer pre-qualification with a soft credit check so you can review potential loan options without damaging your credit score.
Annual Percentage Rates (APRs) for bad credit personal loans typically range from 18.00% to 35.99%. Consumer advocacy organizations and regulators recognize 36% APR as the upper benchmark for affordable personal installment loans. Your specific APR will depend on your income, loan amount, repayment term, and state regulations.
Pre-qualification involves a soft credit inquiry that estimates the loan amounts, rates, and terms you may qualify for. Soft inquiries do not affect your credit score. If you choose to accept an offer and proceed with a lender, the lender will perform a standard hard credit inquiry to verify your details and finalize the loan agreement.
A bad credit personal loan is a multi-month installment loan with fixed monthly payments and APRs capped at 35.99%, allowing you to pay off principal and interest gradually. Payday loans require full repayment within two to four weeks and often carry exorbitant APRs of 400% or higher, frequently trapping borrowers in expensive debt cycles.
To expedite verification, prepare: (1) A government-issued photo ID (driver's license, state ID, or passport), (2) Proof of steady income (recent pay stubs, W-2 forms, or bank statements), (3) An active personal checking account for direct deposit, and (4) Proof of address such as a recent utility bill.
Yes, provided you borrow from a lender that reports your payment activity to the major credit bureaus (Experian, Equifax, and TransUnion). Consistently making on-time, full monthly installments establishes a positive payment track record, which accounts for 35% of your FICO credit score.