Auto Loan Purchase vs. Car Refinancing
Whether you are shopping for a new or used vehicle or seeking relief from an expensive existing car loan, securing transparent digital financing empowers American drivers to avoid dealership markups and save thousands of dollars over the life of their vehicle.
Understanding Auto Purchase Financing vs. Car Refinancing
| Financing Type | Primary Objective | Typical APR Range | Borrowing Limit | Best Suited For |
|---|---|---|---|---|
| New / Used Auto Purchase | Acquiring a vehicle from a dealership or private party seller. | 4.99% – 21.99% | $5,000 – $45,000 | Car buyers seeking pre-approval bargaining power. |
| Standard Auto Refinance | Replacing an existing high-APR loan with lower monthly payments. | 4.49% – 18.99% | Remaining Balance | Drivers whose credit score has improved since purchase. |
| Cash-Out Auto Refinance | Borrowing against vehicle equity to access cash while refinancing. | 5.99% – 22.99% | Up to 125% Loan-to-Value | Vehicle owners needing emergency funds or debt payoff. |
How Much Can You Save by Refinancing Your Car Loan?
Many consumers sign high-interest dealership financing contracts simply because they need immediate transportation. Dealership finance managers often add dealer reserve markup (marking up lender rates by 1.5% to 3.0% for dealer profit).
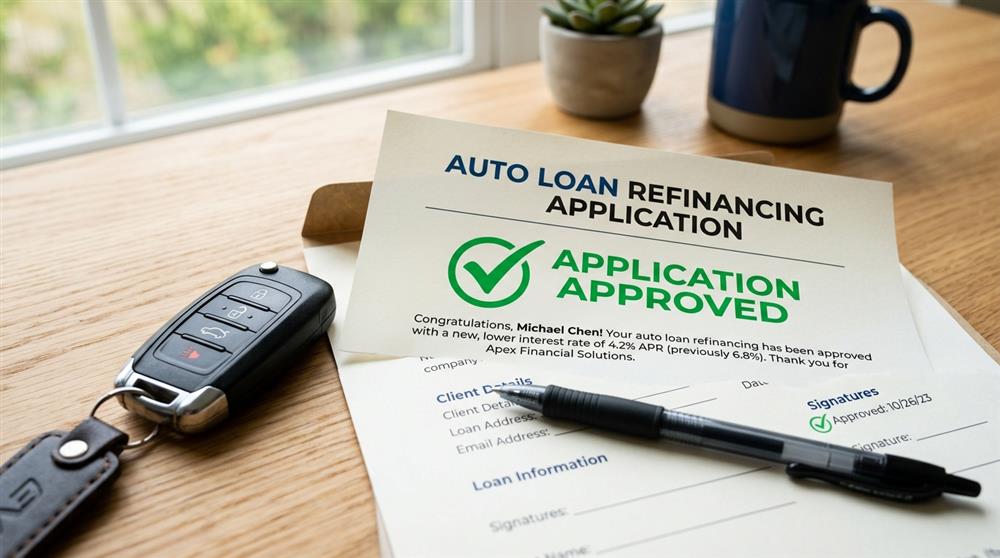
Refinancing with an independent online lender allows you to strip out unnecessary dealer markups and capitalize on improved personal credit or broader interest rate drops. Below is an example of potential savings on a $25,000 auto loan balance:
| Scenario | Remaining Balance | APR | Loan Term | Monthly Payment | Total Interest Paid |
|---|---|---|---|---|---|
| Current Dealership Loan | $25,000 | 14.50% | 60 Months | $588.22 | $10,293.20 |
| Refinanced Online Loan | $25,000 | 7.25% | 60 Months | $497.98 | $4,878.80 |
| Your Total Savings | — | -7.25% | — | Save $90.24 / month | Save $5,414.40 Total |
Eligibility Requirements for US Auto Borrowers
Because auto loans are secured by the vehicle title as collateral, approval standards are often more accommodating than those for unsecured personal loans. To submit an auto inquiry through our network, you must meet these criteria:
- Driver's License & Age: Must hold a valid U.S. driver's license and be at least 18 years old (19 in Alabama and Nebraska).
- Verifiable Earnings: Regular monthly income of at least $1,500 to $1,800 from employment, business, or verified retirement.
- Vehicle Standards: Vehicle must typically be 10 model years or newer with under 120,000 to 140,000 miles.
- Clean Vehicle Title: The vehicle must possess a clean title (branded, salvage, flood, and reconstructed titles are ineligible).
- Active Comprehensive & Collision Insurance: Verifiable auto insurance policy meeting state statutory minimum coverage limits.
Truth in Lending Act (TILA) Compliance Notice
TILA Representative Auto Loan Example
Participating lenders provide full federal disclosures detailing financing charges, loan fees, and amortization schedules before agreement finalization:
- Loan Amount: $20,000.00
- Loan Term: 48 Months (4 Years)
- Representative Fixed APR: 8.49%
- Monthly Installment: $492.74
- Total Interest Paid: $3,651.52
- Total Repayment Amount: $23,651.52
Actual APR, loan amount, and duration depend on vehicle make, model year, mileage, credit profile, and state lending guidelines.
Federal Consumer Protections & Military Lending Act (MLA)
Military Lending Act (MLA): In compliance with federal statute (10 U.S.C. 987), active-duty servicemembers and eligible dependents receive comprehensive borrowing protections, including statutory interest caps (36% MAPR) and full restrictions on arbitrary prepayment penalties.
State DMV & Lending Regulations: Title transfers, lienholder registrations, and refinancing payoffs are conducted in direct accordance with your state department of motor vehicles (DMV / BMV / DOT) and state lending regulators.
Frequently Asked Questions About Auto Loans & Refinancing
Auto refinancing replaces your current high-rate car note with a new loan featuring a lower APR, extended repayment schedule, or both. This directly reduces your monthly interest charges, lowering your regular monthly out-of-pocket payment.
Yes. Because automotive loans are backed by the vehicle as collateral, lenders face less risk than unsecured loans. Our network includes lenders evaluating steady verifiable income, debt-to-income ratios, and vehicle equity for borrowers with fair or subprime credit.
Most participating lenders require the car to be under 10 to 12 model years old, have fewer than 120,000 to 140,000 miles, carry a clean non-salvage title, and maintain a minimum remaining payoff balance of at least $5,000.
No. Initial prequalification inquiries submitted through All Financial Help perform a soft credit pull only, allowing you to review available offers without lowering your FICO credit score.
Yes, if your car's market value exceeds your outstanding loan balance (positive equity), cash-out refinancing enables you to borrow against that equity and receive direct cash for home improvements, debt consolidation, or unexpected bills.