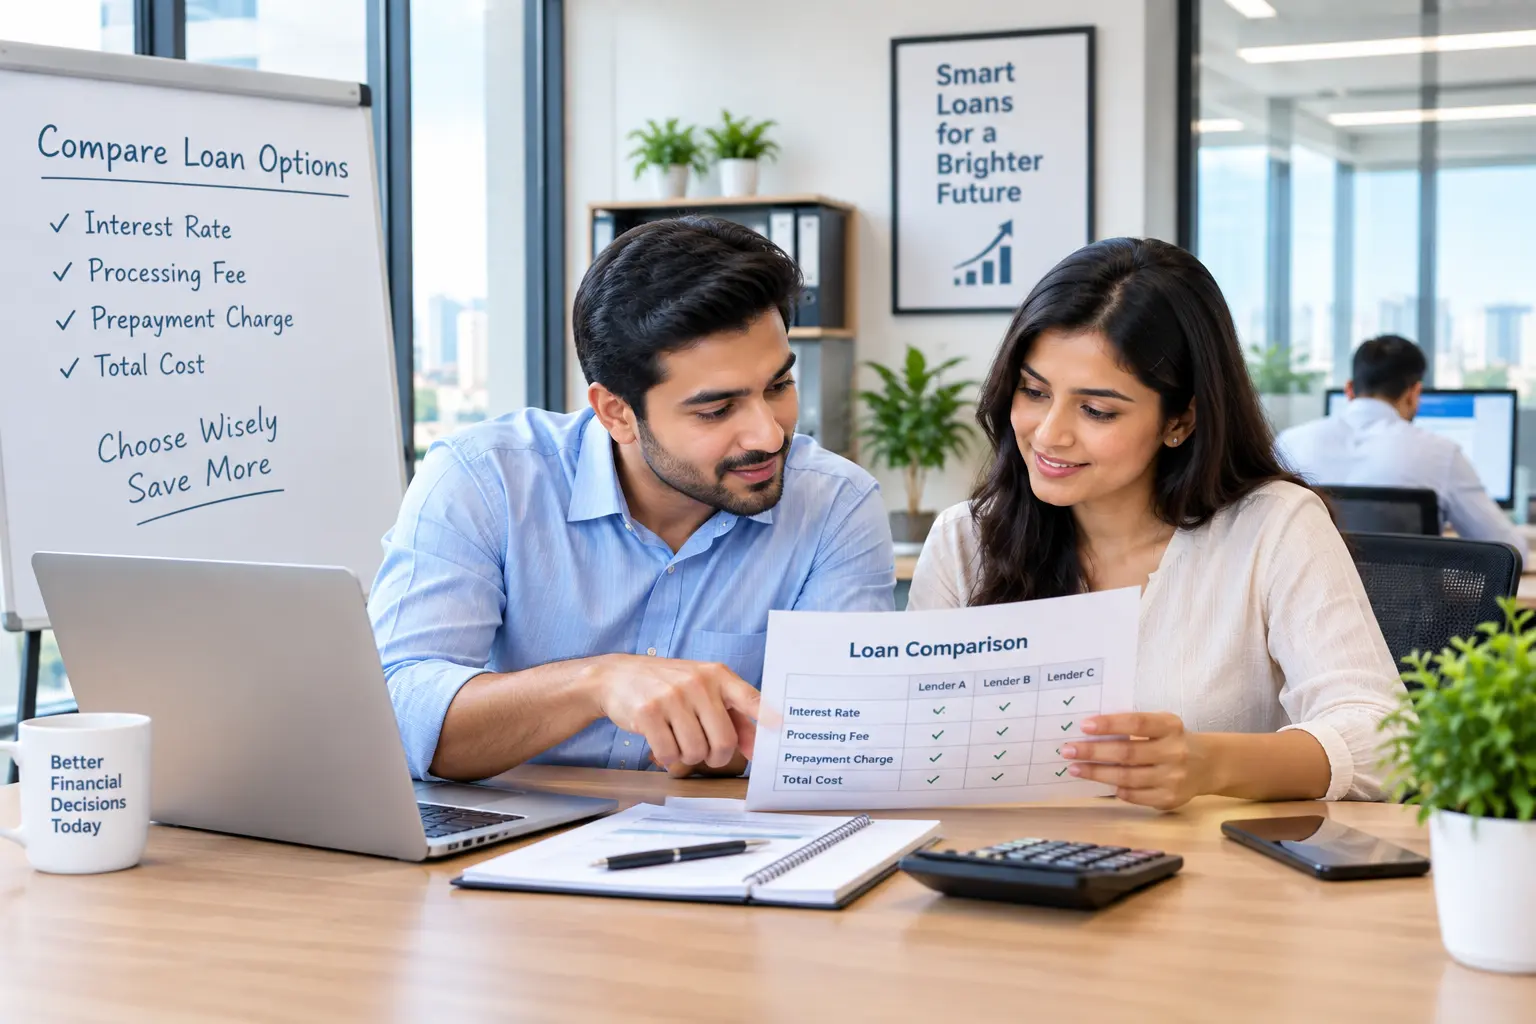

Before taking on new debt, it is important to understand the costs and terms of the loan. Before selecting a loan, consider how its terms may affect your monthly expenses and total repayment amount. Reviewing several loan options can help you find favorable terms while reducing the risk of unexpected charges.
If you are looking for How to Compare Loan Offers and Avoid Hidden Fees, the first step is to look beyond the monthly payment. Interest rates, APR, loan terms, fees, and the total repayment amount can all affect the real cost of borrowing.
Why Should You Compare Loan Offers?
Different lenders may offer different interest rates, repayment periods, fees, and loan amounts. Even a small difference in the interest rate can affect the total cost of a loan.
Comparing multiple offers gives you an opportunity to understand your options before making a decision. For auto loans, the Consumer Financial Protection Bureau recommends comparing factors such as the APR, interest rate, loan length, and total amount financed.
Instead of choosing the first offer you receive, take time to review several options and compare them under similar conditions.
Compare the Interest Rate and APR
The interest rate is one of the most important parts of a loan because it determines the cost of borrowing money. However, you should also pay attention to the Annual Percentage Rate (APR).
APR can provide a broader view of borrowing costs because it can include the interest rate and certain additional fees. This makes it useful when comparing loan offers from different lenders.
When comparing loans, make sure you are comparing APR with APR and not simply looking at one lender's interest rate against another lender's APR.
Look at the Loan Term
The loan term is the amount of time you have to repay the money. A longer repayment period may make your monthly payment smaller, but it can also increase the amount of interest you pay over the life of the loan.
For example, two lenders may offer similar loan amounts, but one may provide a shorter repayment period while the other offers a longer term. The longer loan may appear more affordable each month, but the total repayment could be higher.
Therefore, consider both the monthly payment and the overall cost before choosing an offer.
Check for Fees and Additional Charges
One of the most important parts of How to Choose the Right Loan and Avoid Unnecessary Fees is reviewing all fees associated with the loan.
Depending on the type of loan and lender, possible charges may include:
* Origination fees
* Application fees
* Documentation or processing fees
* Late payment fees
* Prepayment or early repayment charges
* Other lender-specific charges
For personal installment loans, the CFPB notes that fees can add to the overall cost of borrowing, so borrowers should review the lender's disclosures and loan documents carefully.
Ask the lender to explain any fee you do not understand before signing the agreement.
Don't Focus Only on the Monthly Payment
A low monthly payment can look attractive, but it does not necessarily mean the loan is less expensive.
A longer loan term can reduce the amount you pay each month while increasing the total interest paid over time. This is why you should calculate how much you will pay from the beginning to the end of the loan.
When comparing offers, look at:
* Loan amount
* Interest rate
* APR
* Loan term
* Monthly payment
* Total interest
* Total repayment amount
* All applicable fees
This approach can give you a clearer picture of the actual cost of each offer.
Ask Questions Before Accepting a Loan
Before signing a loan agreement, ask the lender questions about anything that is unclear. Find out whether the interest rate is fixed or variable, whether there are additional fees, and whether you can repay the loan early without a penalty.
Also make sure the written loan terms match what the lender originally discussed with you. Reviewing the documents carefully can help you identify unexpected charges before you commit.
Compare Multiple Lenders
One of the easiest ways to find a suitable loan is to compare offers from several lenders. You can consider banks, credit unions, online lenders, and other reputable financing providers depending on the type of loan you need.
Having multiple offers makes it easier to compare rates and fees. Having multiple offers can help you seek more competitive terms.
Final Thoughts
How to Choose the Right Loan and Avoid Unnecessary Fees starts with looking at the complete cost of borrowing rather than choosing a loan based only on its monthly payment. Compare the APR, interest rate, loan term, fees, total interest, and total repayment amount before making your decision.
Reading the loan agreement carefully and asking questions about unfamiliar charges can also help you avoid unexpected costs. By comparing multiple offers and understanding the terms, you can make a more informed borrowing decision that fits your budget and financial goals.